

Is Your Travis County, TX Home Insurance Ready for Tornado and Hail Damage?
The FEMA National Risk Index rates tornado risk in Travis County, where Austin is the county seat, as Very High, higher than 99.7% of U.S. counties. Hail is rated Very High too, higher than 99.4% of U.S. counties, and the county has 538,109 occupied homes according to the U.S. Census. If you live here, the storm itself is only half the problem, because what your policy actually pays after wind or hail depends on a deductible many owners never look up.
Travis County Risk Profile
Overall risk: Relatively High, higher than 97.7% of U.S. counties
| Hazard | Rating | Score (percentile) |
|---|---|---|
| Wildfire | Relatively Moderate | 90.8 |
| Riverine Flooding | Relatively High | 98.3 |
| Tornado | Very High | 99.7 |
| Hail | Very High | 99.4 |
| Strong Wind | Relatively High | 94.8 |
| Lightning | Relatively High | 93.3 |
Source: FEMA National Risk Index. Scores are percentile ranks among all U.S. counties: a score of 90 means higher risk than 90% of counties. Ratings are for the county as a whole.
Travis County at a Glance
- County seat
- Austin
- Largest towns
- Austin, Pflugerville, Manor, Lakeway, Leander
- Occupied homes
- 538,109
- Flood insurance (NFIP) policies in force
- 6,295
- FEMA disaster declarations
- 35 (most recent July 6, 2025)Counts fire, flood, hurricane, severe ice storm, severe storm and winter storm declarations
Sources: U.S. Census Bureau (American Community Survey), FEMA NFIP policy data, FEMA disaster declarations.
Does my Travis County home insurance cover river flooding?
No, a standard homeowners policy excludes flood, so you need separate flood insurance, either through the NFIP or a private flood policy. Travis County’s riverine flooding risk is rated Relatively High, higher than 98.3% of U.S. counties, in the FEMA National Risk Index. FEMA’s National Flood Insurance Program shows 6,295 policies in force in the county, so check now whether yours is one of them.
How tornado risk affects homes in Travis County
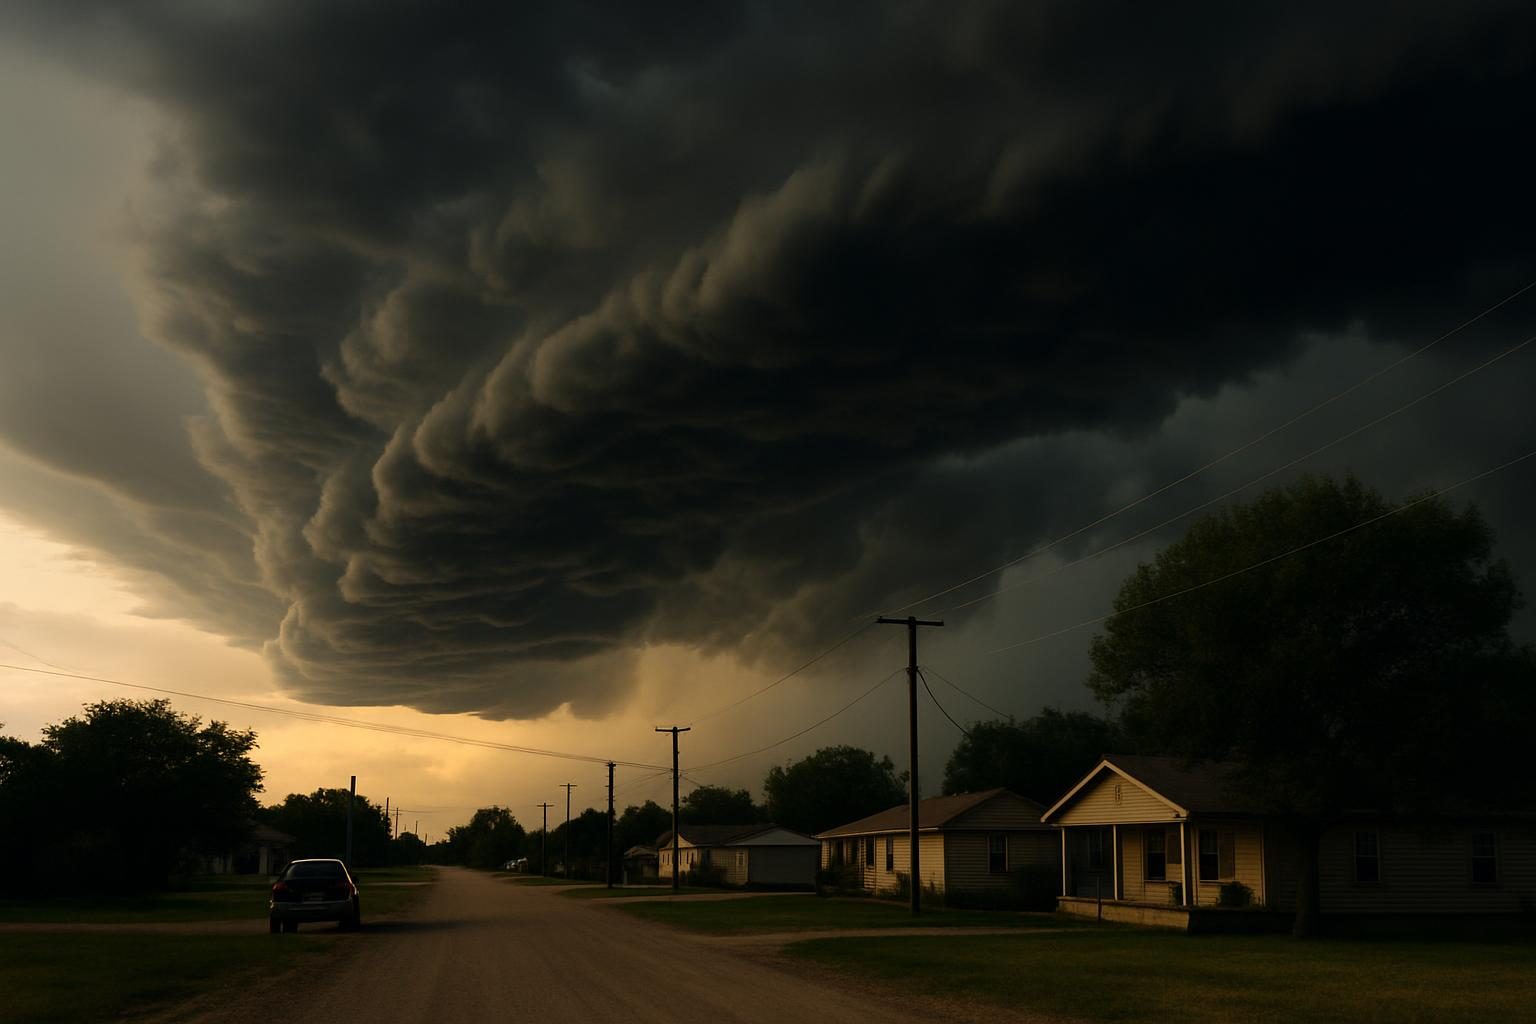
The top hazard here is tornado. The FEMA National Risk Index puts Travis County in the Very High category, higher than 99.7% of U.S. counties. That covers Austin, Pflugerville, Manor, Lakeway and Leander, though the Index reports risk for the county as a whole, not for any one town.
What it does to a house: Tornado damage is rarely one clean event. Roof decking gets torn loose, windows fail, and debris punches through walls, so a single loss can touch the roof, the structure and the contents inside.
- Find your wind and hail deductible on your policy declarations page and write the dollar amount down.
- Check whether your policy has flood coverage. If you have no flood policy, assume you have none.
- Photograph or video every room, the roof and the exterior, and store the files somewhere off your property.
How home insurance treats tornado and hail damage in Travis County
Tornado and wind damage are generally covered the same way fire is under a standard homeowners policy. The question is rarely whether the policy responds. It is how much the insurance company agrees is owed once the deductible comes off.
Hail sits right beside tornado in the ranking. The FEMA National Risk Index rates hail Very High for Travis County, higher than 99.4% of U.S. counties. Hail is typically covered under the same wind and hail provision, so it usually triggers the same separate deductible.
Watch the fight over condition. Insurers often argue that hail marks on an older roof are wear and age instead of storm damage. Keeping dated photos of your roof from before a storm gives you something to put against that argument.
How the separate wind and hail deductible changes what you collect in Travis County
Most Texas policies carry two deductibles. One applies to ordinary losses, and a separate wind or hail deductible applies to storm damage. They are not the same number, and the storm one is usually the larger of the two.
Here is why that matters in a county this exposed. The Index rates strong wind Relatively High, higher than 94.8% of U.S. counties, on top of Very High tornado and hail. A storm in Travis County can be a wind event, a hail event or both, and your payment starts only after the wind and hail deductible is satisfied.
A smaller loss can pay you nothing. If the covered repair estimate lands near your deductible, the insurance company may owe little or no money, even though your home was damaged. The estimate itself becomes the whole game, because every line the insurer leaves out comes straight out of your pocket.
Flood is a different animal. Riverine flooding is rated Relatively High, higher than 98.3% of U.S. counties, and flood is excluded from a standard homeowners policy. FEMA has recorded 35 fire, flood, hurricane, severe ice storm, severe storm and winter storm disaster declarations for Travis County, the latest dated July 6, 2025. Wind deductibles do not apply to flood, because flood is not paid under your homeowners policy at all.
How a public adjuster helps with the wind and hail deductible in Travis County
A claim happens after the damage, and that is when we come in. Licensed Austin public adjusters work for you, never the insurance company, and can document structural damage and personal property losses so the full scope is on paper before the deductible is applied.
The estimate drives the payout. A public adjuster evaluates the scope and cost of covered damage, reviews how your policy applies to that claim, and communicates and negotiates with the insurer. If you are weighing who to trust, read what a public adjuster is and how to deal with the insurance company adjuster before you sign anything.
Disputed, underpaid or denied? Helping with those claims is part of the work, including claims where the insurer calls hail damage wear.
Frequently Asked Questions
How many flood insurance policies are in force in Travis County, TX?
FEMA’s National Flood Insurance Program shows 6,295 policies in force in Travis County. The county has 538,109 occupied homes per the U.S. Census. Flood is excluded from a standard homeowners policy, so a home without NFIP or private flood coverage has no flood protection.
Is the wind and hail deductible in Travis County the same as my regular deductible?
Usually not. Most Texas homeowners policies carry a separate wind or hail deductible, distinct from the main policy deductible. Your declarations page lists both, so find the storm deductible now and write the dollar amount down.
How high is hail risk in Travis County, TX?
The FEMA National Risk Index rates hail risk in Travis County as Very High, higher than 99.4% of U.S. counties. The figure is county level and does not rate any single neighborhood or city.
Does homeowners insurance cover wind damage in Travis County?
Wind and tornado damage are generally covered like fire under a standard homeowners policy. The main catch is the separate wind or hail deductible, which is subtracted before the insurance company pays. Strong wind is rated Relatively High here, higher than 94.8% of U.S. counties.
Final Word: Tornado and Hail Deductibles Decide Your Payout in Travis County
Travis County rates Very High for both tornado and hail, so the likely storm here is one your homeowners policy is built to respond to, but only after the separate wind and hail deductible is met. Know that number before the weather turns, keep your home documented, and treat flood as a separate policy you either have or do not.
Contact ClaimsMate for tornado and hail insurance claim issues. ClaimsMate’s expert and licensed public adjusters represent the policyholder and communicate and negotiate with the insurance company on property claims. Contact us for a no-cost consultation.
Sign up for a free consultation today from ClaimsMate to discover the best path forward for your tornado damage insurance claim.
Public Adjusters Serving Travis County
Sources
Stephanie is a property insurance claim expert with over 20 years of experience working as an insurance adjuster, expert witness, appraiser and umpire. She is passionate about sharing her expertise, knowledge, tips and training to help both property owners and Public Adjusters in their pursuit of effectively managing claims and recovering the claim settlement they deserve after a loss.