

What Should Fisher County, TX Homeowners Check About Hail and Wildfire Insurance Coverage?
The FEMA National Risk Index (https://www.fema.gov/flood-maps/products-tools/national-risk-index) ranks hail as Fisher County's highest natural hazard at Relatively Low, higher than 56.9% of U.S. counties. That is a modest rating, but it applies to the 1,514 homes (U.S. Census occupied housing units) from Roby to Rotan to Hamlin. A low county rating does not stop one bad storm from landing on your roof.
Fisher County Risk Profile
Overall risk: Very Low, higher than 1.9% of U.S. counties
| Hazard | Rating | Score (percentile) |
|---|---|---|
| Wildfire | Very Low | 48.9 |
| Riverine Flooding | Very Low | 2.7 |
| Tornado | Very Low | 14.6 |
| Hail | Relatively Low | 56.9 |
| Strong Wind | Very Low | 14 |
| Lightning | Very Low | 2.4 |
Source: FEMA National Risk Index. Scores are percentile ranks among all U.S. counties: a score of 90 means higher risk than 90% of counties. Ratings are for the county as a whole.
Fisher County at a Glance
- County seat
- Roby
- Largest towns
- Rotan, Roby, Hamlin
- Occupied homes
- 1,514
Sources: U.S. Census Bureau (American Community Survey).
Is hail a real risk for my home in Fisher County, TX?
Yes, but a modest one. FEMA rates Fisher County’s hail risk as Relatively Low, higher than 56.9% of U.S. counties, so hail can still damage a Roby, Rotan, or Hamlin roof even in a quiet year. Treat it as a risk worth preparing for, not one to ignore.
How hail damages homes in Fisher County, TX
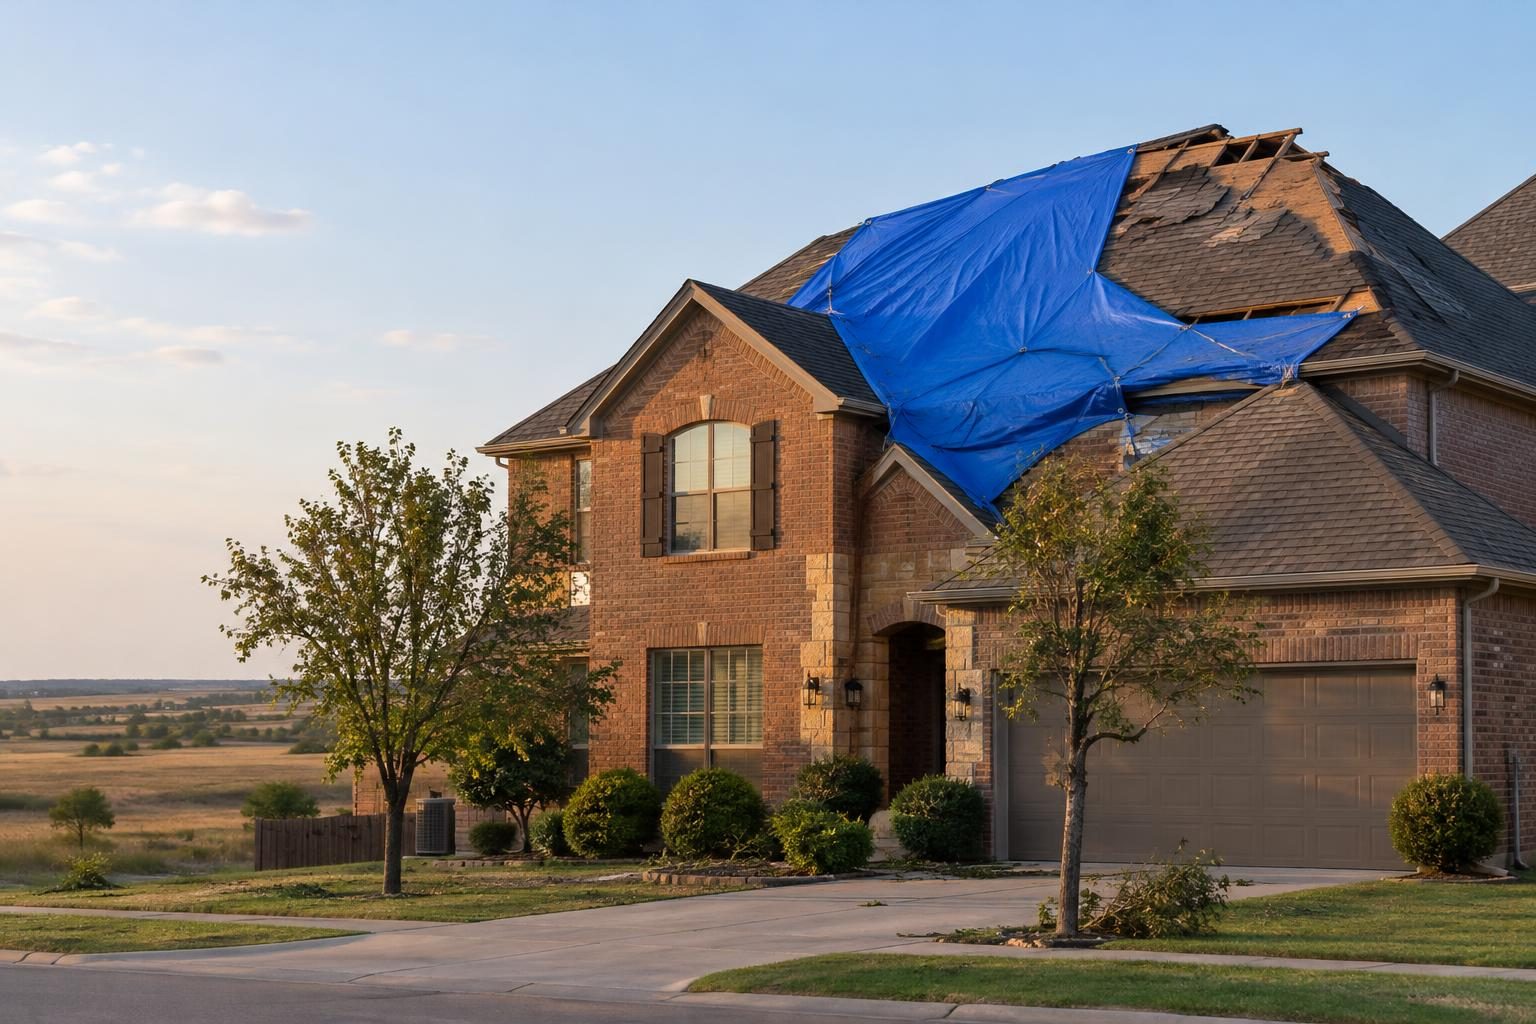
Hail is the hazard most likely to cost a Fisher County homeowner money, because the National Risk Index puts it ahead of every other covered hazard here at Relatively Low. It rarely crushes a house. It wears the roof out early by bruising shingles, knocking off granules, and cracking vents, flashing, and gutters.
Hidden damage is the problem. A roof in Roby or Hamlin can look fine from the driveway while the mat underneath is fractured and leaks start months later.
- Look at your roof, gutters and window screens after any hail event, even a small one.
- Check the metal on vents and flashing, where dents show up first.
- Photograph the date and the damage before any repair.
What Homeowners Insurance Covers in Fisher County: Wind and Hail, Fire
- Wind, Hail and Tornado: Tornado and wind damage are generally covered by a standard homeowners policy, but most policies carry a separate wind or hail deductible, distinct from the main policy deductible.
- Fire and Wildfire: Fire is a covered peril under a standard homeowners policy. The real fight is usually over how much is owed, not whether it is covered at all.
ClaimsMate’s licensed public adjusters represent the policyholder, never the insurance company, on property insurance claims.
How wildfire risk differs from hail in Fisher County, TX
Wildfire is Fisher County’s second-ranked covered hazard, rated Very Low by FEMA, and it scored 48.9. Hail tends to hit a roof in minutes, while a grass or brush fire on open land near Rotan or Roby can spread over hours and reach fences, outbuildings and the edges of a property.
Know your outbuildings. Barns, sheds and detached garages on rural Fisher County lots are often insured differently from the house, so know what each one is covered for.
Why smoke and soot damage reaches past the burned area in Fisher County
In a Fisher County fire, smoke and soot damage almost always extends beyond the rooms that burned. Smoke travels through HVAC ducts, attic spaces and wall cavities, so a fire in one room of a Hamlin home can leave residue and odor in rooms the flames never touched.
- Gray film on walls and surfaces far from the fire.
- A smoky smell when the heat or air conditioning runs.
- Discolored vents, light fixtures, and ceiling corners.
How a public adjuster handles smoke and soot damage in Fisher County
A licensed public adjuster can document smoke and soot damage across your whole Fisher County home, not only the burned rooms. That includes soot in ductwork, attic insulation, contents and finishes in rooms the insurance company’s estimate skipped.
The fight is usually about scope. If an estimate for your Roby or Rotan home covers only the visible fire damage, an adjuster can evaluate the full scope and cost of covered damage and negotiate for the rest. You can also read how to deal with the insurance company’s adjuster before that conversation starts.
It helps to know who you are dealing with. What a public adjuster does is simple to explain, and it is worth knowing before a loss.
Frequently Asked Questions
How many homes in Fisher County face hail and fire risk?
The U.S. Census counts 1,514 occupied housing units in Fisher County. FEMA’s risk ratings apply to the county as a whole, so every home from Roby to Rotan to Hamlin shares the same county-level hail and wildfire rating.
What does Fisher County’s Very Low wildfire rating mean for my house?
FEMA rates Fisher County wildfire risk as Very Low, but it is still a real possibility on open, dry land. The rating describes the county overall, not your lot, so clearing brush near your home still matters.
Why Fisher County fire and hail claims get underpaid
Even with a Very Low overall county rating of 1.9, the real danger in Fisher County is a claim that pays less than the damage costs. Roofs bruised by hail and houses filled with smoke are exactly the kinds of losses where the first estimate comes in low.
If a loss does happen in Roby, Rotan, or Hamlin, Texas public adjusters at ClaimsMate can document the full extent of hail and smoke damage and negotiate with the insurance company when an estimate falls short. Ask for a no-cost consultation through Find a Public Adjuster or (877) 202-0204.
Sign up for a free consultation today with ClaimsMate to discover the best path forward for your hail damage insurance claim.
Public Adjusters Serving Fisher County
Sources
Stephanie is a property insurance claim expert with over 20 years of experience working as an insurance adjuster, expert witness, appraiser and umpire. She is passionate about sharing her expertise, knowledge, tips and training to help both property owners and Public Adjusters in their pursuit of effectively managing claims and recovering the claim settlement they deserve after a loss.