

Is Your Collin County, TX Home Insurance Prepared for Tornado and Hail Damage?
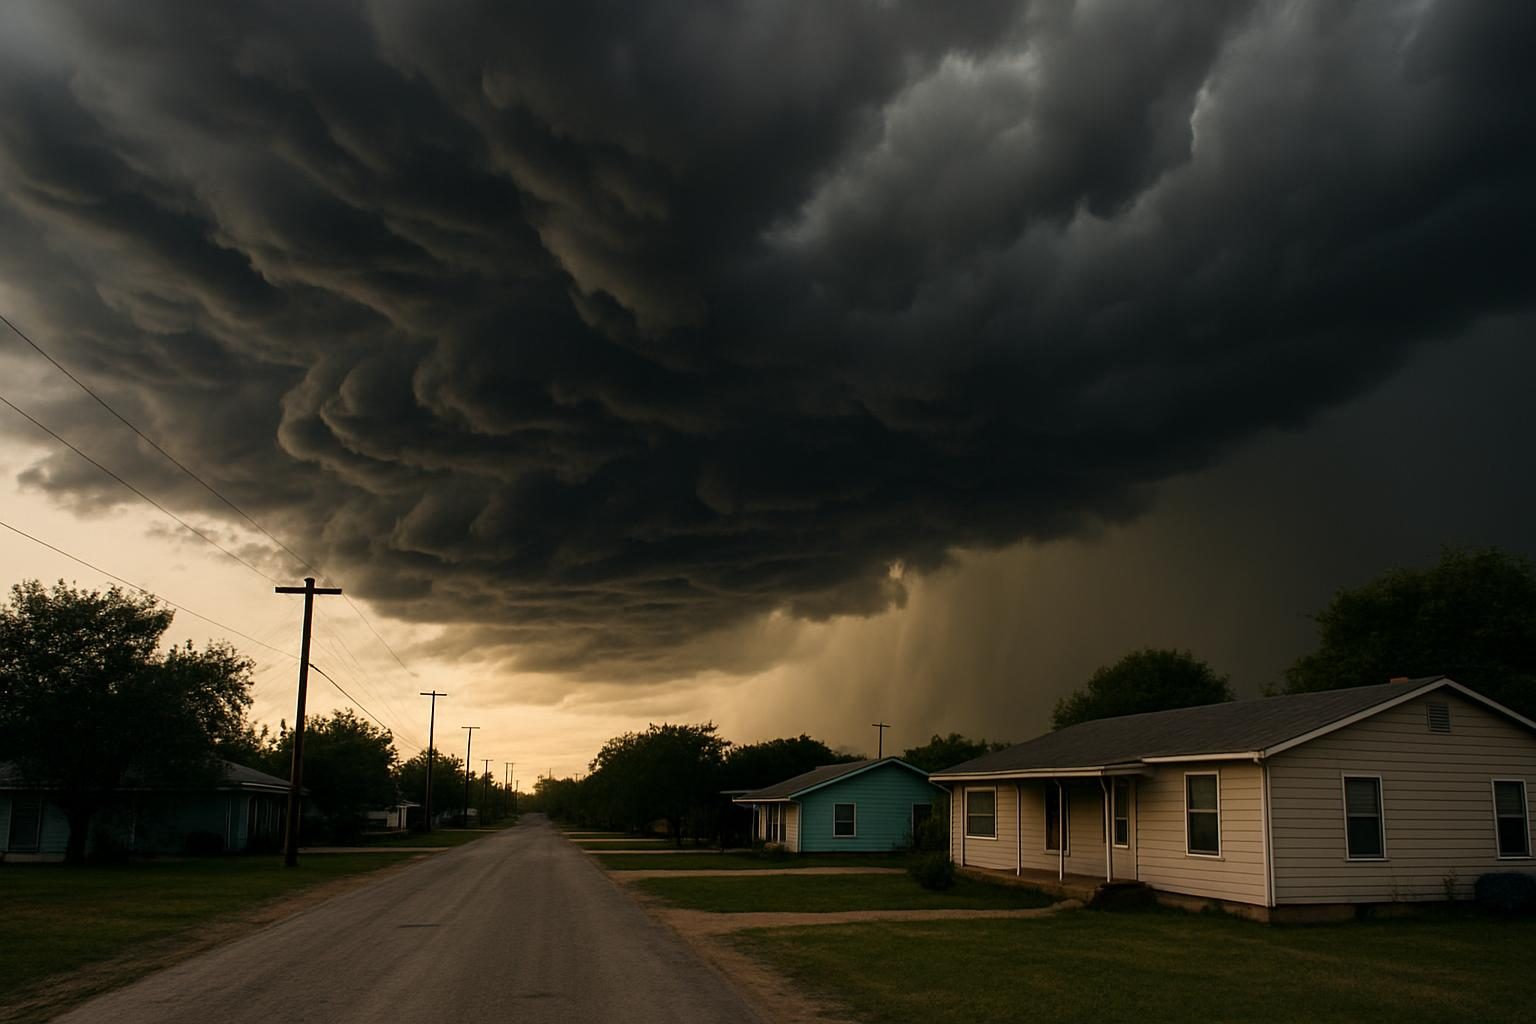
The FEMA National Risk Index rates Collin County's overall natural hazard risk as Relatively High, higher than 98.9% of U.S. counties, and it rates both tornado and hail risk as Very High, each higher than 99.9% of U.S. counties. That matters for the 383,675 occupied homes the U.S. Census counts here, from McKinney (the county seat) to Plano, Frisco, Allen and Wylie. Before a storm hits, the details of your policy decide how much of a repair bill you carry yourself.
Collin County Risk Profile
Overall risk: Relatively High, higher than 98.9% of U.S. counties
| Hazard | Rating | Score (percentile) |
|---|---|---|
| Wildfire | Relatively Low | 81 |
| Riverine Flooding | Relatively High | 96.8 |
| Tornado | Very High | 99.9 |
| Hail | Very High | 99.9 |
| Strong Wind | Relatively High | 87.7 |
| Lightning | Relatively Moderate | 67.7 |
Source: FEMA National Risk Index. Scores are percentile ranks among all U.S. counties: a score of 90 means higher risk than 90% of counties. Ratings are for the county as a whole.
Collin County at a Glance
- County seat
- McKinney
- Largest towns
- Plano, McKinney, Frisco, Allen, Wylie
- Occupied homes
- 383,675
- Flood insurance (NFIP) policies in force
- 1,451
- FEMA disaster declarations
- 17 (most recent May 17, 2024)Counts fire, flood, hurricane, severe ice storm and severe storm declarations
Sources: U.S. Census Bureau (American Community Survey), FEMA NFIP policy data, FEMA disaster declarations.
Does my homeowners insurance cover tornado damage in Collin County, TX?
Yes, in most cases. Tornado and wind damage are generally covered the same way fire is under a standard homeowners policy. The catch is the deductible: many Texas policies apply a separate wind or hail deductible, so find that number now, before a storm, not after.
Questions to ask your insurance agent this week about tornado and hail in Collin County
Start with the deductible. With tornado and hail both rated Very High here, a wind or hail claim is among the likeliest ones you will ever file. Ask your agent these questions and get the answers in writing:
- What is my wind and hail deductible, and is it a flat dollar amount or a percentage of my home’s insured value?
- Does it differ from my main deductible? Which one applies if a storm brings both wind and water into the house?
- How is my roof paid, at replacement cost or actual cash value, and does that change as the roof ages?
- Are there cosmetic damage limits for hail dents on metal, gutters or siding?
- What is my coverage for living expenses if a tornado makes the house unlivable?
What a Collin County homeowners policy covers and leaves out for tornado, hail and flood
Wind is covered, water is not. A standard homeowners policy generally treats tornado and wind damage the way it treats fire: covered, subject to your limits and deductibles. Hail damage to your roof and exterior typically falls under the same wind and hail provisions.
Flood sits outside the policy. Rising water from a creek or river is not paid by homeowners insurance. Riverine flooding is rated Relatively High here, higher than 96.8% of U.S. counties, so it is a real gap. Protection comes only from a separate flood policy, through FEMA’s National Flood Insurance Program or a private carrier.
Few households hold that policy. FEMA’s NFIP shows 1,451 flood insurance policies in force in Collin County, set against 383,675 occupied homes. FEMA also counts 17 disaster declarations in the county for fire, flood, hurricane, severe ice storm and severe storm incidents, the latest dated 2024-05-17. See the FEMA National Risk Index for the county-level ratings.
How the separate wind and hail deductible changes what you actually collect in Collin County
The deductible comes off first. Say your policy carries a wind and hail deductible set as a percentage of your home’s insured value. A roof and exterior repair that looks large on paper can leave a smaller check than you expect, because that deductible is subtracted from the covered damage before the insurer pays anything.
Small damage can mean no payment. If the insurer’s estimate of covered hail damage comes in below your wind and hail deductible, you collect nothing. That is why the scope of the estimate matters as much as the policy itself: every roof section, vent, gutter and window screen counted or missed moves the total relative to a fixed deductible.
Know which deductible applies. A single storm can involve hail, wind-driven rain and tornado debris. Insurers may sort those into different categories, and the category can decide which deductible they apply. Ask your agent how your policy handles that, and find your number today.
How a public adjuster helps with a wind or hail claim in Collin County
Before a loss, the work is yours. Find your wind and hail deductible on your declarations page, confirm whether you hold flood insurance, and photograph your roof, exterior and rooms now while they are undamaged. Keep those photos somewhere off the property.
After a loss, we represent you. ClaimsMate’s licensed public adjusters work for the policyholder, never the insurance company. They document structural damage and personal property losses, review your policy’s coverage for the claim, evaluate the scope and cost of covered damage, and negotiate with the insurer. If you are weighing options, Plano public adjusters serve homeowners in this part of the county, and our guide on dealing with the insurance company adjuster explains what to expect on that side of the table.
Frequently Asked Questions
How high is tornado risk in Collin County, TX?
The FEMA National Risk Index rates tornado risk in Collin County as Very High, higher than 99.9% of U.S. counties. The ratings are county level, so they describe the county as a whole, not a single city or street.
How many flood insurance policies are in force in Collin County?
FEMA’s National Flood Insurance Program shows 1,451 policies in force in Collin County. The U.S. Census counts 383,675 occupied homes here. Riverine flooding is rated Relatively High, so check whether your home has flood coverage.
Is a separate wind and hail deductible common on Collin County policies?
Most Texas homeowners policies carry one, separate from the main deductible. It may be a flat amount or a percentage of your home’s insured value. Look at your declarations page or ask your agent which applies to you.
Does homeowners insurance in Collin County pay for flood damage from a creek or river?
No. Standard homeowners policies do not pay for flood damage. With riverine flooding rated Relatively High in Collin County, you would need a separate flood policy, through NFIP or a private insurer.
Final Word: Tornado and Hail Damage in Collin County Comes Down to Your Deductible
Collin County ranks Very High for both tornado and hail, so assume a wind or hail claim is a matter of when. Know your separate wind and hail deductible now, because it sets how much of any repair bill you pay yourself. And remember that flood needs its own policy.
Contact ClaimsMate for wind and hail claim issues. ClaimsMate’s expert and licensed public adjusters evaluate the scope and cost of covered damage and negotiate with your insurance company on your behalf. Contact us for a no-cost consultation.
Sign up for a free consultation today from ClaimsMate to discover the best path forward for your tornado damage insurance claim.
Public Adjusters Serving Collin County
Sources
Stephanie is a property insurance claim expert with over 20 years of experience working as an insurance adjuster, expert witness, appraiser and umpire. She is passionate about sharing her expertise, knowledge, tips and training to help both property owners and Public Adjusters in their pursuit of effectively managing claims and recovering the claim settlement they deserve after a loss.