

Meadow View Fire in Amarillo, TX: Does Your Policy Cover Fire Damage?
The NIFC WFIGS live wildfire feed lists the Meadow View Fire in Potter County, Texas, at 1,262 acres with 95 percent containment, discovered April 6, 2026. The same feed lists the cause as undetermined and the fuel as short grass and brush (2 feet), with Amarillo (ZIP code 79101) as the listed town and ZIP. If fire or smoke reached your property, your homeowners policy is where your recovery starts, and the list of what you lost is where the biggest argument usually begins.
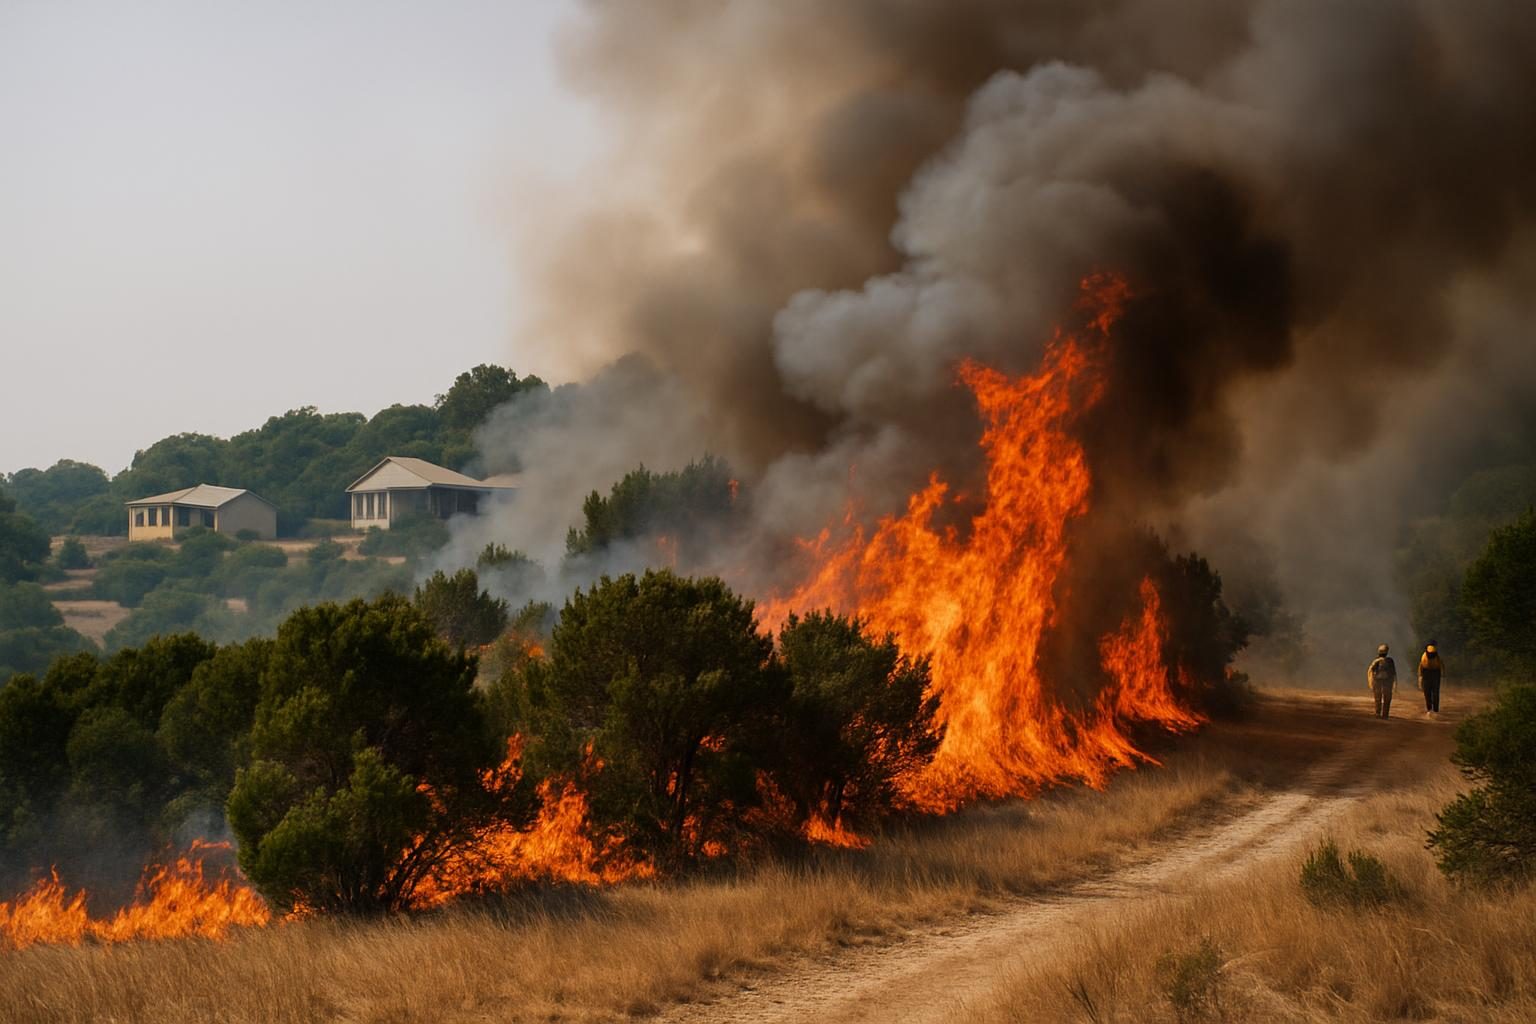
Latest reported details
- Fire
- Meadow View Fire
- Location
- Amarillo, Potter County
- Acres burned
- 1,262
- Containment
- 95%
- Discovered
- April 6, 2026
- Cause
- Undetermined
Does homeowners insurance cover fire damage from the Meadow View Fire in Amarillo?
Yes, fire is a covered peril under a standard homeowners policy, so wildfire damage to a home is the kind of loss the policy is written for. Once it is safe, call your insurer to open a claim and photograph everything before you clean up or throw anything away. The harder question is usually how much the company agrees to pay.
Mistakes that cost Amarillo homeowners money during the Meadow View Fire
Safety first. Follow instructions from local fire and law enforcement officials, and do not return to a burned or smoky area until you are told it is safe. Containment numbers change, so check the current status at nifc.gov.
Evidence disappears fast. Insurers pay for what you can show them. These are the mistakes that cost people the most:
- Tossing damaged items before they are photographed.
- Starting cleanup first. Take photos and video of every room and the outside before you move or wash anything.
- Delaying the call. Open the claim with your insurer as soon as it is safe, and write down the claim number, the date and who you spoke with.
- Guessing at values in a recorded statement or a rushed form.
Before you give a statement, read our guide on how to deal with the insurance company adjuster. Remember that the adjuster works for the company.
How homeowners insurance treats fire damage in Potter County
Fire is covered, so coverage is rarely the fight. A standard policy generally pays for fire damage to the house, other structures and your belongings, up to your limits and after your deductible. Smoke damage from a covered fire is part of the same conversation, and our page on fire damage insurance claims goes deeper.
The real dispute is the dollar amount. Insurers argue over the scope of repairs, the price of materials and labor, and how much to subtract for age and wear.
- Your dwelling limit and your personal property limit
- Whether belongings are paid at replacement cost or actual cash value
- Your deductible
- Any coverage for living expenses if you cannot stay in the home
If the home is destroyed, see our guide to total loss insurance claims.
Contents valuation disputes after a fire in Amarillo
The company’s number is rarely your number. A contents claim is an item-by-item list, and the insurer prices every line. Low replacement prices, heavy depreciation and vague descriptions like “misc. electronics” can shrink the total fast.
Replacement cost or actual cash value matters. Actual cash value subtracts depreciation, so a ten-year-old couch may be valued at a fraction of what a new one costs. Know which method your policy uses before you look at any offer.
- Go room by room, including closets, garage and storage
- Record brand, model, age and what you paid, where you can
- Gather receipts, bank and card statements, online order history and old photos
- Keep damaged remains until the insurer has had a chance to inspect them
Ask how each figure was reached. Do not accept a lump sum or flat percentage without seeing the line-by-line pricing and depreciation. If the numbers do not match what it costs to replace your belongings today, say so in writing.
How a public adjuster helps with a contents dispute in Amarillo
Someone on your side of the table. ClaimsMate’s licensed public adjusters represent you, never the insurance company. On a fire claim, they document your structural damage and personal property losses, then prepare and organize the claim.
Built around your policy. They review the policy’s coverage for your claim, evaluate the scope and cost of covered damage, and communicate and negotiate with the insurer when its contents valuation falls short. They also help with disputed, underpaid or denied claims.
Next step. To talk it through, see our Amarillo public adjusters page, learn what a public adjuster is, or use Find a Public Adjuster or call (877) 202-0204 for a free consultation.
Frequently Asked Questions
Will my insurer pay to replace belongings burned in a wildfire?
A standard homeowners policy generally covers personal property damaged by fire, up to your limit and after your deductible. How much you receive depends on whether the policy pays replacement cost or actual cash value, and on the prices the insurer assigns to each item.
Is smoke damage covered if flames never reached my house?
Smoke damage from a covered fire is generally handled as part of the fire claim. Photograph soot, odor-affected items and discolored surfaces, and report it to your insurer. Your policy language and the insurer’s inspection will decide the details.
Should I throw away items the fire ruined?
No, not before they are photographed and listed. Keep damaged items or their remains until the insurer has inspected them or approved disposal in writing. Throwing things away early makes it harder to prove what you owned and what it was worth.
What can I do if the insurer’s contents total is too low?
Ask for the line-by-line pricing and depreciation, then compare it with your receipts, photos and current replacement prices. Dispute errors in writing. A licensed public adjuster can help with disputed or underpaid claims.
Final Word: Contents Claims After the Meadow View Fire in Amarillo Are Often Disputed
Fire coverage is usually not the question. What counts is how your belongings are valued, so document every item and do not accept a number you cannot trace.
Contact ClaimsMate for wildfire insurance claim issues. ClaimsMate’s expert and licensed public adjusters document structural damage and personal property losses and negotiate with the insurance company. Contact us for a no-cost consultation.
Sign up for a free consultation today from ClaimsMate to discover the best path forward for your wildfire insurance claim.